The Tax Department Has a Second View of Your Financial Life: Why AIS Should Be Reconciled With Your Books
· 2 min read
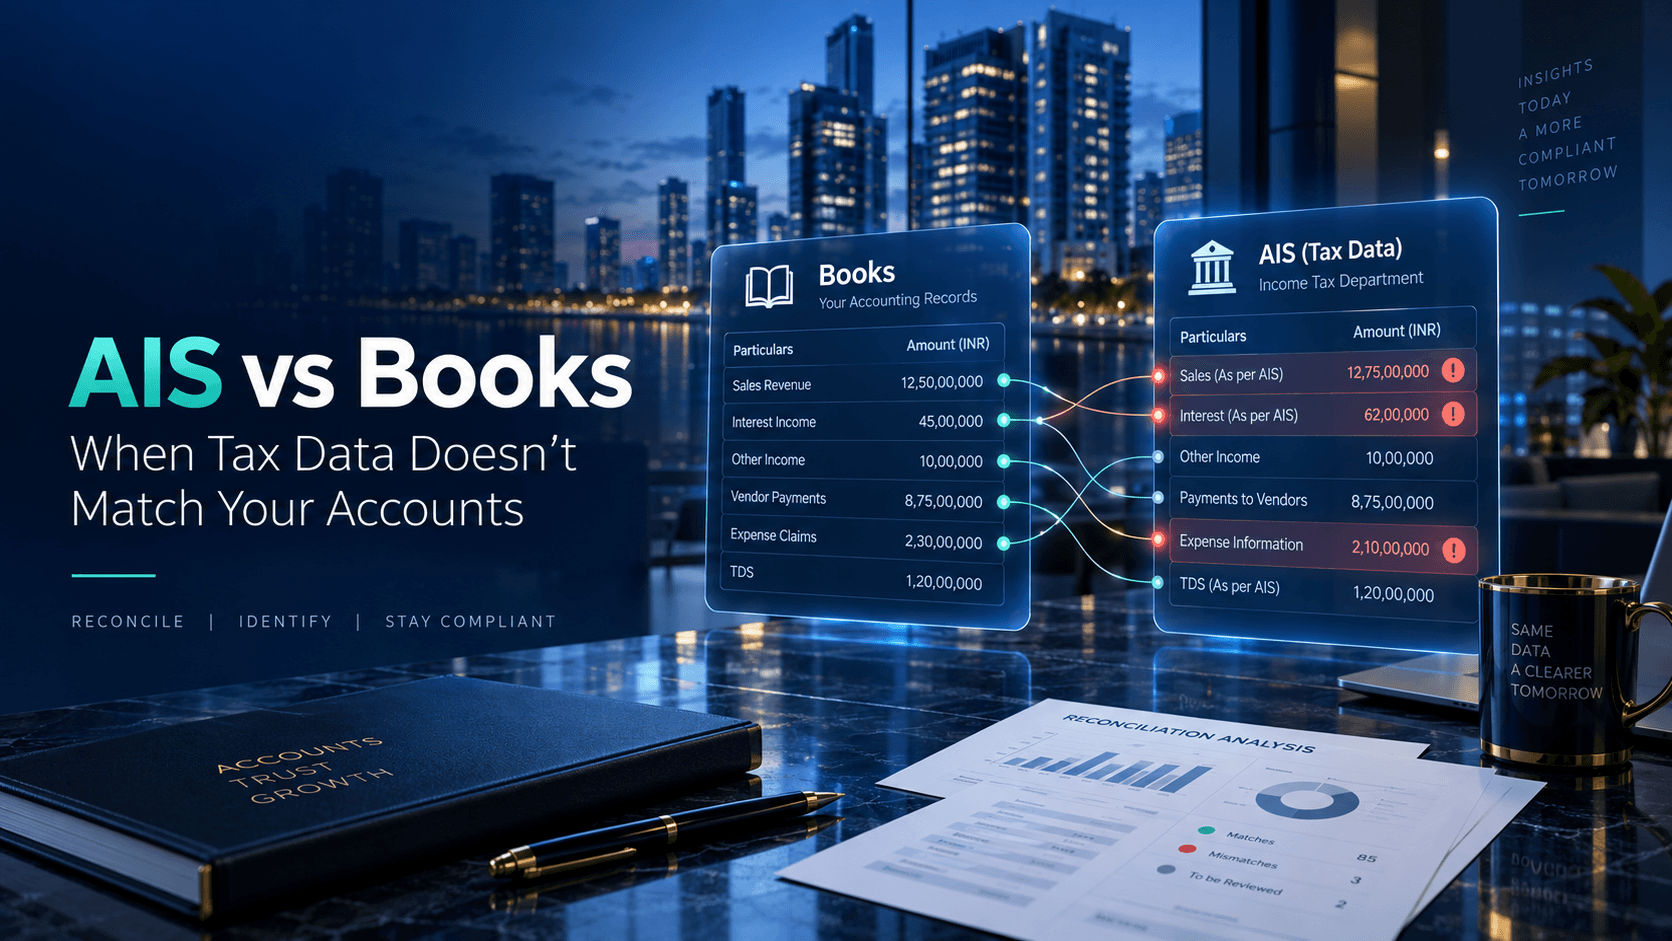
The Annual Information Statement gives the Income Tax Department an external view of a taxpayer’s financial activity. When AIS and accounting records differ, the objective should not be to force the numbers to match, but to identify, explain and document every material difference.
AIS Is More Than a Filing Reference
Your books are no longer the only financial dataset relevant to income-tax compliance.
AIS can contain information reported through external sources, including:
TDS and TCS Financial transactions Tax payments Refunds GST-related information Other reported financial data
This creates a simple control question:
Do your books explain what the tax system sees?
A Simple Example Particular Amount Receipts in books ₹2.40 crore Receipts reflected externally ₹2.53 crore Difference ₹13 lakh
The correct response is not simply to change the tax return.
Finance should first identify:
Which transactions created the ₹13 lakh difference Whether there is a timing difference Whether something was reported twice Whether a transaction is missing from the books Whether third-party information is incorrect
The objective is explanation, not artificial matching.
Why AIS and Books May Differ
Common reasons include:
Timing differences Duplicate reporting Incorrect third-party reporting Gross versus net reporting Wrong financial year Accounting omissions Different transaction classification
A mismatch does not automatically mean additional tax.
An unexplained mismatch is the real concern.
What Should Be Reconciled?
Finance teams should review material differences relating to:
Interest income TDS and TCS Securities transactions High-value transactions Tax payments Refunds Other externally reported receipts
For every material exception, record:
Amount in AIS Amount in books Difference Reason Supporting evidence Action taken From Tax Filing to Tax Intelligence
Traditional process:
Close books Download AIS Prepare return File
Better process:
Record Reconcile Identify Investigate Document File
This helps businesses detect issues before the return is finalised.
What a Better Dashboard Should Show
Instead of only:
Income Tax Return: Filed
A useful dashboard should show:
AIS match percentage Unmatched transactions Value under review TDS differences Open exceptions Items requiring action
Example:
94% records matched ₹13 lakh under review 17 unmatched transactions 4 open exceptions
That is more useful than a simple filing status.
Final Takeaway AIS is an external financial-data source AIS and books may legitimately differ Every material difference should have a reason Supporting evidence should be preserved Reconciliation should happen before filing
The key question is not:
Does AIS match the books?
It is:
Can every material difference be explained?
That is the shift from tax filing to tax intelligence.